Skip to Content
xtroverso
  • Scope of Work
  • How It Works
    • How XTROVERSO Works
    • FAQ
  • Framework
    • Why XTROVERSO Is Different
    • Framework and Controls
    • Verification and Compliance Checks
    • Cultural Manifesto
  • Knowledge
  • About
  • Contact
  • 0
  • 0
  • Nederlands English (US)
  • CLIENT AREA
xtroverso
  • 0
  • 0
    • Scope of Work
    • How It Works
      • How XTROVERSO Works
      • FAQ
    • Framework
      • Why XTROVERSO Is Different
      • Framework and Controls
      • Verification and Compliance Checks
      • Cultural Manifesto
    • Knowledge
    • About
    • Contact
  • Nederlands English (US)
  • CLIENT AREA
  • All Blogs
  • Ledger & Tax
  • Dutch Acquisition Debt Needs Its Own Business Case
  • Dutch Acquisition Debt Needs Its Own Business Case

    Related-party acquisition debt needs its own business reason. Check the transaction, cash route, loan terms and accounting records before relying on Dutch inte.
    August 27, 2026 by
    Linda Pavan

    Dutch interest deductions on related-party acquisition debt depend on the reasons for the internal transaction and the loan. A commercial acquisition alone may not support the deduction. Without a clear financing rationale, the Dutch company may report higher taxable profit and pay more cash tax.

    Why this matters

    Article 10a can restrict interest, financing costs and currency results on certain related-party debt. A finance director needs a file that links business reasons to contracts, cash movements and ledger entries. A denied deduction increases cash tax and can affect acquisition returns, forecasts, dividends and loan covenants. Article 15b is a separate test. Current guidance restricts net interest above both 24.5% of profit and €1 million.

    Example

    A group buys a company with bank finance. Six months later, it transfers the shares internally and lends to a Dutch holding company. The purchase may have a commercial purpose. The later loan still needs an explanation. Why is the Dutch company the borrower? Where did the cash go? Do the amount, timing, rate, maturity, repayments and security match the external funding? Minutes, bank statements, contracts and ledger entries should show the same sequence.

    XTROVERSO tips

    • Map the full transaction. Put the acquisition, share transfers, capital movements, loan drawdowns and repayments on one timeline. Add the related contracts and board approvals.
    • Follow the cash. Match each loan entry to bank statements and its actual use. Check whether cash moved through other group companies before reaching the Dutch borrower.
    • Compare the loan terms. Record the amount, drawdown date, interest rate, maturity, repayment plan and security. Compare them with the external funding said to support the internal loan.
    • Check the books against the file. Confirm that interest accruals, intercompany balances and tax calculations follow the contracts and actual payments. Resolve differences while records remain available.
    • Test forecasts again. Review cash tax, acquisition returns, covenants, dividend planning and tax provisions if the deduction relies on incomplete evidence. Assess Article 10a and the separate interest limits individually.

    Need to check whether your acquisition loan, cash trail and tax file still agree? Our team can help identify the gaps

    CONTACT US

    The data, sourcing, and analysis behind this article were conducted by Linda Pavan. AI was not used to identify sources, build the factual basis, or produce the analytical judgment contained here. AI was used only as a drafting aid. The final English text was personally reviewed, edited, and approved by Linda Pavan before publication.

    References

    • Rechtspraak – Amsterdam Court of Appeal, ECLI:NL:GHAMS:2026:2322
    • Wettenbank – Article 10a, Dutch Corporate Income Tax Act 1969
    • Belastingdienst – Private equity, debt push-down and external funding
    • Belastingdienst – Generic earnings stripping limitation
    • Rijksoverheid – Guidance on article 15b Wet Vpb 1969
    • Taxence – Fiscale motieven staan renteaftrek concernlening in de weg
    in Ledger & Tax
    # Article 10a GOVERNANCE LEDGER & TAX acquisition finance corporate income tax corporate tax debt push-down earningsstripping fiscal unity related-party loans
    Linda Pavan August 27, 2026
    Share this post

    Share

    Linda Pavan

    Certified ZENTRIQ™ Auditor and co-founder of XTROVERSO™, Linda brings decades of expertise in ledger management and tax compliance. 

    With a rigorous yet pragmatic approach, she ensures financial systems are not just accurate, but aligned with transparency, trust, and long-term resilience.

    BOOK A MEETING

    Linda Pavan

    Gecertificeerd ZENTRIQ™ Auditor en medeoprichter van XTROVERSO™, brengt Linda tientallen jaren expertise mee in ledgerbeheer en fiscale compliance.

    Met een rigoureuze maar pragmatische aanpak zorgt zij ervoor dat financiële systemen niet alleen accuraat zijn, maar ook in lijn liggen met transparantie, vertrouwen en veerkracht op lange termijn.

    BOOK A MEETING

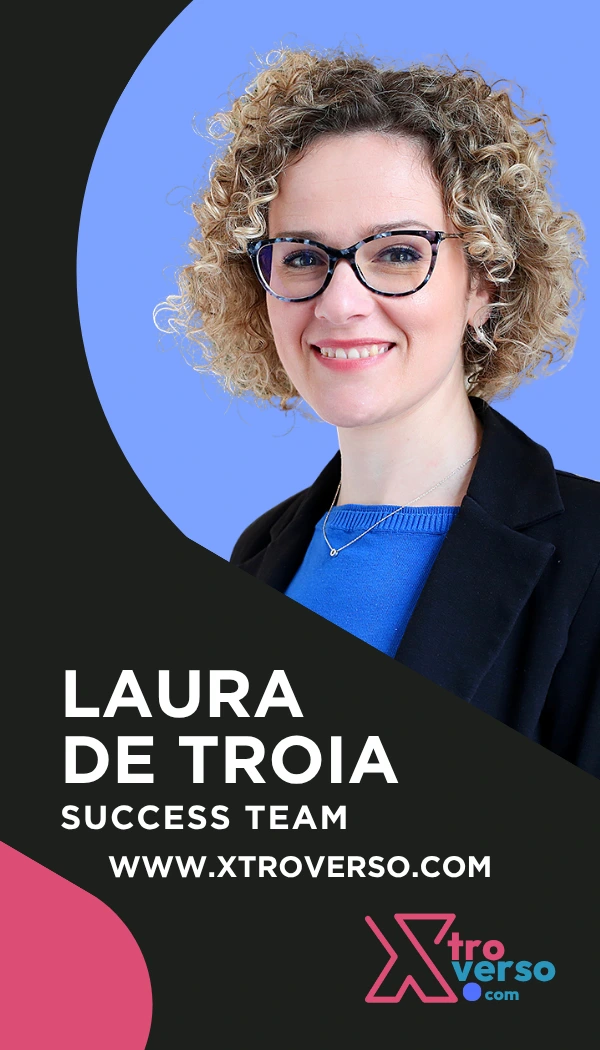
    Laura De Troia

    Laura, con la sua empatia naturale e il suo forte senso del servizio, fa sì che ogni cliente si senta ascoltato, supportato e valorizzato. È impegnata a costruire relazioni durature e porta chiarezza, calore e coerenza in ogni interazione, contribuendo a rafforzare la fiducia e ad elevare l’esperienza del cliente.

    BOOK A MEETING

    Laura De Troia

    Laura, con su empatía natural y su fuerte vocación de servicio, hace que cada cliente se sienta escuchado, acompañado y valorado. Está comprometida con la construcción de relaciones duraderas y aporta claridad, calidez y coherencia en cada interacción, contribuyendo a fortalecer la confianza y a elevar la experiencia del cliente.

    BOOK A MEETING

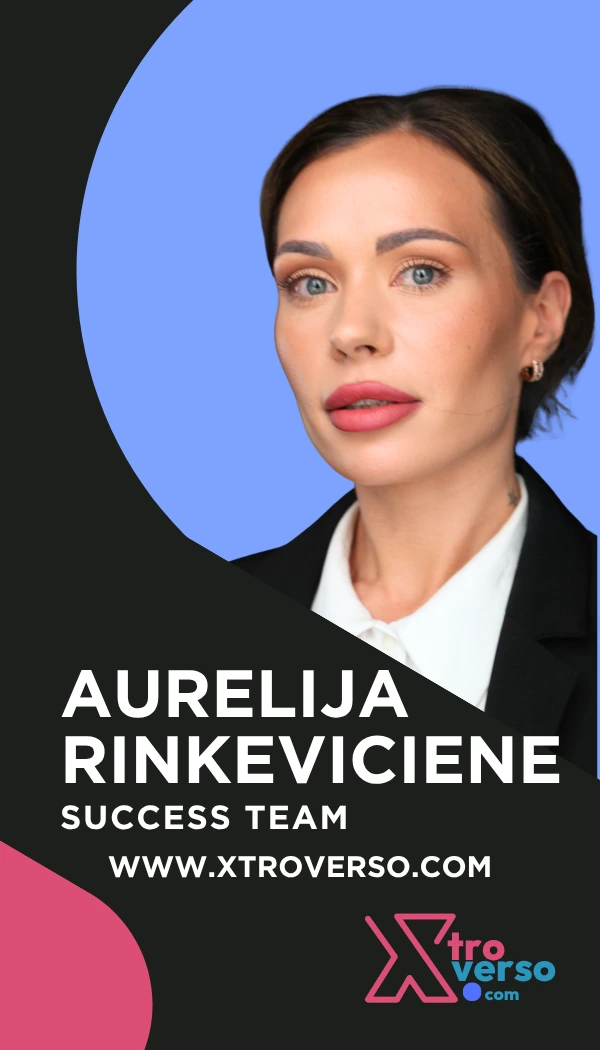
    Aurelija

    Aurelija, turinti natūralią empatiją ir stiprų rūpinimosi klientu jausmą, pasirūpina, kad kiekvienas klientas jaustųsi išgirstas, palaikomas ir vertinamas. Ji yra atsidavusi ilgalaikių santykių kūrimui, o kiekvienam kontaktui suteikia aiškumo, šilumos ir nuoseklumo, taip stiprindama pasitikėjimą ir dar labiau gerindama kliento patirtį.

    BOOK A MEETING

    Tags
    Article 10a GOVERNANCE LEDGER & TAX acquisition finance corporate income tax corporate tax debt push-down earningsstripping fiscal unity related-party loans
    Our blogs
    • Ledger & Tax
    • Compliance
    • Market Pulse
    • Human Resources
    • Governance
    • Real Estate

    Read Next
    A One-Year Stay Can Raise Inheritance Tax
    A temporary right to stay in an inherited home can affect inheritance tax, property costs and estate cash. The will’s wording determines the valuation route.
    XTROVERSO

    Company-control framework and integrated fiscal services for sole proprietors and B.V.s in the Netherlands.

    XTROVERSO is a registered trade name of WIGEPA B.V. Defined fiscal and professional services are performed by Pavan Geraedts Adviseurs under its own professional responsibility.

    • 2017-26  © XTROVERSO 
      KvK: 70402787
      BTW: NL858307790B01
      BECON: 685811

    Explore
    • About 
    • Knowledge
    • Contact
    • FAQ
    • WORK WITH US
    • PRESS ROOM
      Book Your Intake
    • Client Login
    Services
    • Scope of Work
    • How XTROVERSO Works
    • Book Your Intake
    Framework

    How XTROVERSO Works
    Why XTROVERSO Is Different
    Framework & Controls
    Verification & Compliance Checks
    Cultural Manifesto

    Legal

    Terms & Conditions
    Data & Privacy Statement
    Cookie Policy

    Office
    De Stuwdam 33
    3815 KM Amersfoort
    The Netherlands

    Open map

    Website Logo

    Respecting your privacy is our priority.

    Allow the use of cookies from this website on this browser?

    We use cookies to provide improved experience on this website. You can learn more about our cookies and how we use them in our Cookie Policy.

    Allow all cookiesOnly allow essential cookies