Passa al contenuto
xtroverso
  • How it works
  • From €250
  • Ambito di lavoro
  • Chi siamo
  • Knowledge
  • 0
  • 0
  • Nederlands English (US) Italiano Español
  • AREA CLIENTI
xtroverso
  • 0
  • 0
    • How it works
    • From €250
    • Ambito di lavoro
    • Chi siamo
    • Knowledge
  • Nederlands English (US) Italiano Español
  • AREA CLIENTI
XTROVERSO
Come funziona Da €250 Ambito Chi siamo Knowledge
NL EN IT ES
Portale clienti Prenota intake ↗
Menu
Come funziona XTROVERSO Il tuo miglior sonno Perché diverso Ambito di lavoro Framework e controlli Verifica Manifesto culturale FAQ Chi siamo Lavora con noi Ufficio stampa Knowledge Contatti Prenota intake Portale clienti
NL EN IT ES
  • Tutti i blog
  • LINDA PAVAN
  • When Interest Is Paid Before the Tax Deduction Arrives
  • When Interest Is Paid Before the Tax Deduction Arrives

    Dutch interest limits can separate the date interest is paid from the date tax relief becomes available. Property structures and cross-border groups need a cle.
    1 settembre 2026 di
    XTROVERSO

    Dutch companies can pay loan interest now while part of the tax deduction is delayed. In 2026, the generic limit applies when net interest exceeds both 24.5% of profit and €1 million. Qualifying property entities can have a zero threshold. The gap can increase taxable profit and tighten cash.

    Why this matters

    Interest leaves the bank on its payment date. The deduction depends on taxable profit and room under the limit. Disallowed interest may carry forward. It can be used only when later profit provides deduction room. Lower rent, a weak trading year, or refinancing can reduce that room. In 2026, corporate income tax is 19% up to €200,000 of taxable profit and 25.8% above it. Qualifying property entities have no €1 million threshold.

    Example

    A BV owns a commercial building rented to external tenants. Rent covers interest, maintenance and repayment. Its accounts record the full interest cost. The tax calculation may deduct only part of that interest this year. Taxable profit can then exceed the accounting result. The BV pays the lender and may owe more current tax. Carried-forward interest helps only when later profit leaves enough deduction room. The owner needs one forecast for rent, interest, repayment, tax and carried-forward interest.

    XTROVERSO tips

    • Map every material loan. Record the lender, borrower, rate, security, repayment date and business purpose. Match each loan to the legal entity earning the related income.
    • Add tax timing to the cash forecast. Show interest paid, interest deductible this year and interest carried forward as separate lines in the planning file.
    • Check property entities separately. Review the asset mix and rental relationships. Confirm whether at least 70% of assets are property rented outside the group.
    • Review cross-border payment routes. Check related parties, ownership percentages, receiving jurisdictions and payment flows. Include interest, royalties and dividends in the review.
    • Test the file before signing. Compare the contract, entity chart, bank movements, accounts and tax position before refinancing or restructuring. They should describe the same financing arrangement.

    Need a clear view of debt, tax deductions and cash timing? XTROVERSO can review the file before you sign or refinance

    CONTACT US

    The data, sourcing, and analysis behind this article were conducted by Linda Pavan. AI was not used to identify sources, build the factual basis, or produce the analytical judgment contained here. AI was used only as a drafting aid. The final English text was personally reviewed, edited, and approved by Linda Pavan before publication.

    References

    • Taxence — Kabinet kritisch op versoepeling Europese renteaftrekbeperking
    • Belastingdienst — Changes to Dutch corporate income tax in 2026
    • Rijksoverheid — Effect of the earnings-stripping measure
    • Rijksoverheid — Property measure and anti-fragmentation rules
    • Belastingdienst — Withholding tax on interest and royalties
    • Belastingdienst — Dutch participation exemption and 5% boundary
    • Rijksoverheid — Research into abuse of the earnings-stripping measure
    • Wettenbank — Corporate Income Tax Act 1969, Article 15b
    in LINDA PAVAN
    # Dutch tax LEDGER & TAX business finance cash flow corporate tax cross-border tax earnings stripping interest deduction property companies property entities
    XTROVERSO 1 settembre 2026
    Condividi articolo

    Condividi

    Linda Pavan

    Auditor certificato ZENTRIQ™ e co-fondatore di XTROVERSO™, Linda porta decenni di esperienza ingestione dei registri e conformità fiscale. 

    Con un approccio rigoroso ma pragmatico, assicura che i sistemi finanziari non siano solo accurati, ma allineati contrasparenza, fiducia e resilienza a lungo termine.

    PRENOTA UN INCONTRO

    Linda Pavan

    Auditor certificato ZENTRIQ™ e co-fondatore di XTROVERSO™, Linda porta decenni di esperienza nella gestione dei registri e nella conformità fiscale.

    Con un approccio rigoroso ma pragmatico, assicura che i sistemi finanziari non siano solo accurati, ma anche in linea con trasparenza, fiducia e resilienza a lungo termine.

    PRENOTA UN INCONTRO

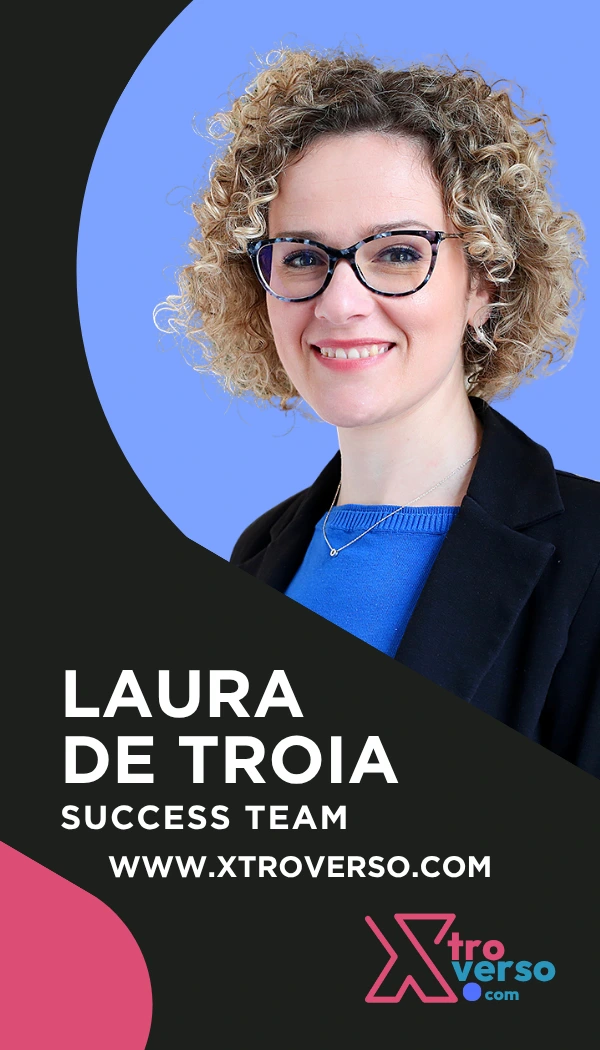
    Laura De Troia

    Laura, with her natural empathy and strong sense of service, ensures that every customer feels heard, supported, and valued. She is committed to building lasting relationships and brings clarity, warmth, and consistency to every interaction, helping to strengthen trust and elevate the customer experience.

    PRENOTA UN INCONTRO

    Laura De Troia

    Laura, con la sua empatia naturale e la sua forte vocazione al servizio, fa sì che ogni cliente si senta ascoltato, accompagnato e valorizzato. È impegnata nella costruzione di relazioni durature e porta chiarezza, calore e coerenza in ogni interazione, contribuendo a rafforzare la fiducia e a elevare l'esperienza del cliente.

    PRENOTA UN INCONTRO

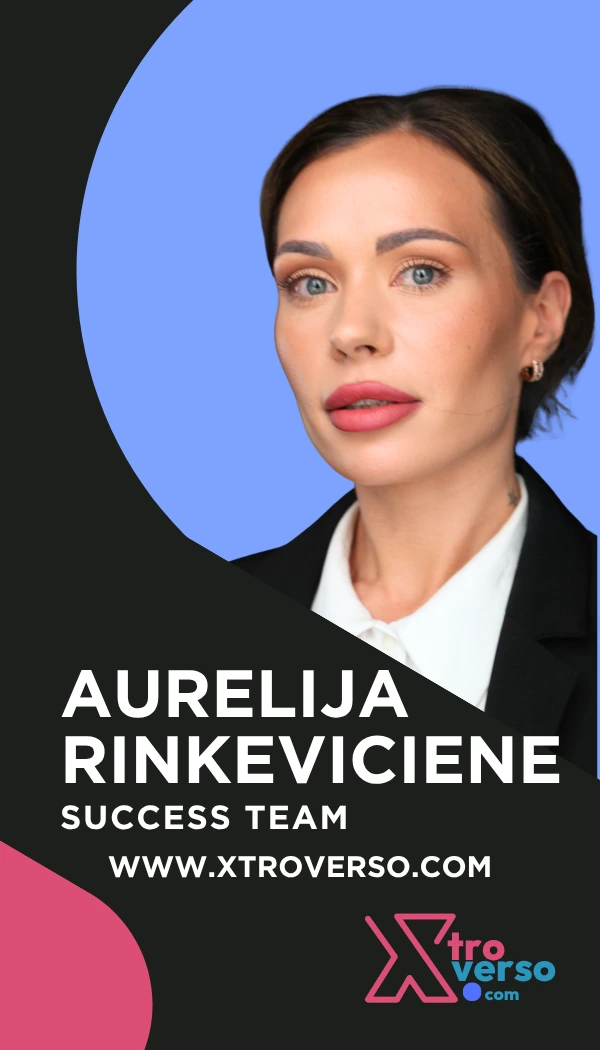
    Aurelija

    Aurelija, con la sua empatia naturale e un forte senso di cura per il cliente, si assicura che ogni cliente si senta ascoltato, supportato e apprezzato. È dedicata alla creazione di relazioni a lungo termine e fornisce chiarezza, calore e coerenza in ogni contatto, rafforzando così la fiducia e migliorando ulteriormente l'esperienza del cliente.

    PRENOTA UN INCONTRO

    Etichette
    Dutch tax LEDGER & TAX business finance cash flow corporate tax cross-border tax earnings stripping interest deduction property companies property entities
    I nostri blog
    • LINDA PAVAN
    • IVA
    • FATTURAZIONE E LIBRO MASTRO
    • BUSTA PAGA
    • Governance
    • Real Estate

    Leggi successivo
    Tax Corrections Can Reopen Partner Allocations
    A Dutch tax ruling gives fiscal partners wider allocation choices after a lawful additional assessment. Both tax files and the cash effect need review.
    XTROVERSO

    Intelligenza artificiale + esperienza umana + supervisione professionale.

    Servizio

    Come funziona Il tuo miglior sonno Ambito di lavoro Perché diverso FAQ

    Framework

    Framework e controlli Verifica Manifesto culturale

    Studio

    Su XTROVERSO Lavora con noi Ufficio stampa Contatti Prenota intake Portale clienti Pavan Geraedts ↗

    Legale

    Termini e condizioni Informativa privacy Cookie policy

    Pratica responsabile

    XTROVERSO

    Amministrazione aziendale per ZZP e VOF

    Dichiarazione IVA e deposito con Pavan Geraedts Adviseurs

    Ufficio

    De Stuwdam 33-35

    3815 KM Amersfoort

    Paesi Bassi

    Incontri solo su appuntamento

    Contatti

    +31 (0)85 401 9174

    hello@xtroverso.com

    KvK 70402787

    VAT NL858307790B01

    BECON 685811

    Confine professionale

    Amministrazione a cura di XTROVERSO

    Dichiarazione IVA e deposito a cura di Pavan Geraedts Adviseurs (sempre inclusi); ulteriore revisione fiscale dove il pacchetto lo richiede

    XTROVERSO e Pavan Geraedts Adviseurs operano come studi coordinati. Le responsabilità restano definite nel pacchetto applicabile e nelle condizioni dell'incarico.

    © 2017–2026 XTROVERSO. Tutti i diritti riservati.

    XTROVERSO™

    Amministrazione aziendale per freelance (ZZP) e VOF nei Paesi Bassi, con revisione fiscale coordinata dove il pacchetto lo richiede.

    XTROVERSO è un nome commerciale registrato di WIGEPA B.V. Dichiarazione IVA e deposito sono sempre eseguiti da Pavan Geraedts Adviseurs sotto la propria responsabilità professionale; ulteriori servizi fiscali seguono il pacchetto.

    • 2017-26  © XTROVERSO 
      KvK: 70402787
      BTW: NL858307790B01
      BECON: 685811

    Esplora
    • Chi siamo 
    • Conoscenza
    • Contatto
    • Domande frequenti
    • LAVORA CON NOI
    • SALA STAMPA
      Prenota il tuo intake
    • Login cliente
    Servizi
    • Ambito di lavoro
    • Come funziona XTROVERSO
    • Prenota il tuo intake
    Framework

    Come funziona XTROVERSO
    Perché XTROVERSO è diverso
    Framework & controlli
    Verifica & compliance
    Manifesto culturale

    Legale

    Termini e condizioni
    Informativa dati & privacy
    Cookie policy

    Ufficio
    De Stuwdam 33
    3815 KM Amersfoort
    Paesi Bassi

    Apri mappa

    Website Logo

    Rispetto della tua privacy è la nostra priorità.

    Permettere l'uso dei cookie da questo sito web su questo browser?

    Utilizziamo i cookie per offrire un'esperienza migliorata su questo sito web. Puoi scoprire di più sui nostri cookie e su come li utilizziamo nella nostra Politica sui cookie.

    Consenti tutti i cookieConsenti solo i cookie essenziali