Saltar al contenido
xtroverso
  • How it works
  • From €250
  • Alcance del trabajo
  • Nosotros
  • Conocimiento
  • 0
  • 0
  • Nederlands English (US) Italiano Español
  • ÁREA DE CLIENTES
xtroverso
  • 0
  • 0
    • How it works
    • From €250
    • Alcance del trabajo
    • Nosotros
    • Conocimiento
  • Nederlands English (US) Italiano Español
  • ÁREA DE CLIENTES
XTROVERSO
Cómo funciona Desde €250 Alcance Nosotros Conocimiento
NL EN IT ES
Portal del cliente Reserva intake ↗
Menú
Cómo funciona XTROVERSO Tu mejor descanso Por qué diferente Alcance del trabajo Marco y controles Verificación Manifiesto cultural FAQ Nosotros Trabaja con nosotros Sala de prensa Conocimiento Contacto Reserva intake Portal del cliente
NL EN IT ES
  • Todos los blogs
  • LINDA PAVAN
  • Low DGA Salary in 2026 Starts With Ownership
  • Low DGA Salary in 2026 Starts With Ownership

    Practical XTROVERSO guidance on Low DGA Salary in 2026 Starts With Ownership: records, tax evidence, cash control, invoices, and decisions founders can act on.
    2 de julio de 2026 por
    XTROVERSO

    For 2026, Dutch DGA payroll checks focus first on whether the person works for a BV or cooperative in which they hold a substantial interest. The salary position matters because low pay must be supported by ownership facts, actual work, market comparison, group wages, and payroll processing.

    Why this matters

    A low DGA salary is not mainly a cash-flow question. The customary-wage rule applies when someone works for a company or cooperative in which that person, possibly together with a fiscal partner, has a substantial interest. In practice, the 5% line often starts the discussion, and shares, options, profit rights, liquidation rights, and voting rights can all be relevant. Once the rule applies, the 2026 wage must normally be at least the highest of three amounts: the wage from the most comparable employment, the wage of the highest-paid employee at the company or a connected company, and €58,000. Cash pressure can matter, but it does not replace the wage comparison. A lower salary needs a file that explains the work, the market value of that work, the group situation, and the payroll treatment.

    Example

    A founder owns more than 5% of a BV and works in the business. The BV has uneven sales and wants to keep cash available for suppliers, stock, software, and staff. That cash concern is understandable, but it is not enough by itself. The first question is whether the founder falls under the customary-wage rule. If yes, the BV must compare the role with a real market wage and check whether anyone in the company or a connected company earns more. If the founder works limited hours in a simple role, a lower market wage may be defensible. If the founder is effectively running the business full time, managing staff, finance, commercial risk, and daily decisions, the file must support why the wage is lower than the normal benchmark.

    XTROVERSO tips

    • Start with ownership and work Check whether the person has a substantial interest and actually works for the BV or cooperative. A job title alone is not enough. A hired CEO without a substantial interest is different from a founder-director-shareholder who works in the business.
    • Do not treat €58,000 as the only number For 2026, €58,000 is only one of the three benchmarks. The wage of the most comparable employment and the wage of the highest-paid employee in the company or a connected company can lead to a higher amount.
    • Build evidence before payroll closes Document the role, hours, responsibilities, sector, complexity, comparable wages, and group wages. Old benchmark notes can become weak when wages in the market move.
    • Keep cash arguments specific Cash pressure may support a lower wage only when the story is concrete. Show why paying the higher wage would affect continuity, liquidity, stock, or assets needed for the business. A general loss or a preference to keep money in the BV is not enough.
    • Make the payroll administration match the position If the DGA receives less than the customary wage, the difference may have to be processed as fictitious wage for payroll tax purposes. Also check current-account debt, dividends, management fees, and other withdrawals. A low salary position becomes fragile when value leaves the BV in another way.
    • Ask early if the position is material For a significant or sensitive lower-wage position, advance consultation can help. The request should explain the work, comparable wages, the highest employee wage, connected companies, and the reason for no wage or lower wage.

    Want to check whether your DGA salary position is defensible before payroll closes?

    CONTACT US

    The data, sourcing, and analysis behind this article were conducted by Linda Pavan. AI was not used to identify sources, build the factual basis, or produce the analytical judgment contained here. AI was used only as a drafting aid. The final English text was personally reviewed, edited, and approved by Linda Pavan before publication.

    References

    • Belastingdienst - Applicability gate: DGA or substantial-interest holder
    • Belastingdienst - 2026 customary-wage benchmark
    • Belastingdienst Kennisgroepen - Connected companies and highest-paid employee
    • Belastingdienst - Payroll filing cadence
    • Rechtspraak - Court signal: narrow financial-distress acceptance
    • Rechtspraak - Supreme Court purpose and comparison method
    • Belastingdienst Kennisgroepen - Pre-incorporation BV period
    • Belastingdienst - Vooroverleg and evidence checklist
    en LINDA PAVAN
    # Belastingdienst DGA payroll DGA salary Dutch BV Dutch BV salary LEDGER & TAX customary wage gebruikelijk loon low DGA salary 2026 payroll tax substantial interest
    XTROVERSO 2 de julio de 2026
    Compartir esta publicación

    Compartir

    Linda Pavan

    Auditor certificado ZENTRIQ™ y cofundadora de XTROVERSO™, Linda aporta décadas de experiencia engestión de libros y cumplimiento fiscal.. 

    Con un enfoque riguroso pero pragmático, asegura que los sistemas financieros no solo sean precisos, sino que estén alineados contransparencia, confianza y resiliencia a largo plazo..

    RESERVA UNA REUNIÓN

    Linda Pavan

    Auditor certificado ZENTRIQ™ y cofundadora de XTROVERSO™, Linda aporta décadas de experiencia en gestión de libros y cumplimiento fiscal.

    Con un enfoque riguroso pero pragmático, asegura que los sistemas financieros no solo sean precisos, sino que también estén alineados con la transparencia, la confianza y la resiliencia a largo plazo.

    RESERVA UNA REUNIÓN

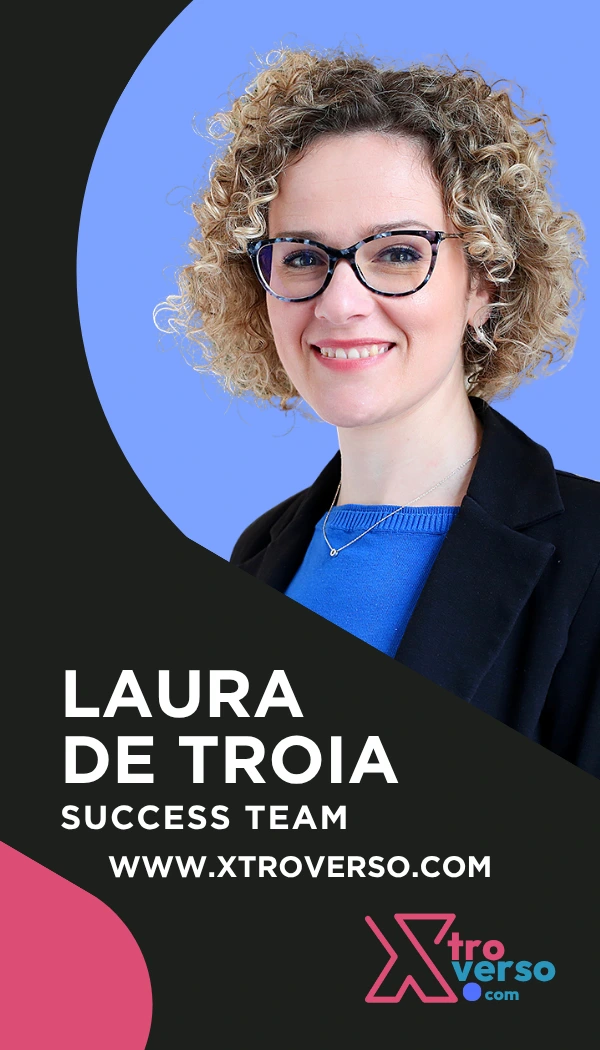
    Laura De Troia

    Laura, con su empatía natural y su fuerte sentido del servicio, hace que cada cliente se sienta escuchado, apoyado y valorado. Está comprometida a construir relaciones duraderas y aporta claridad, calidez y coherencia en cada interacción, contribuyendo a fortalecer la confianza y a elevar la experiencia del cliente.

    RESERVA UNA REUNIÓN

    Laura De Troia

    Laura, con su empatía natural y su fuerte vocación de servicio, hace que cada cliente se sienta escuchado, acompañado y valorado. Está comprometida con la construcción de relaciones duraderas y aporta claridad, calidez y coherencia en cada interacción, contribuyendo a fortalecer la confianza y a elevar la experiencia del cliente.

    RESERVA UNA REUNIÓN

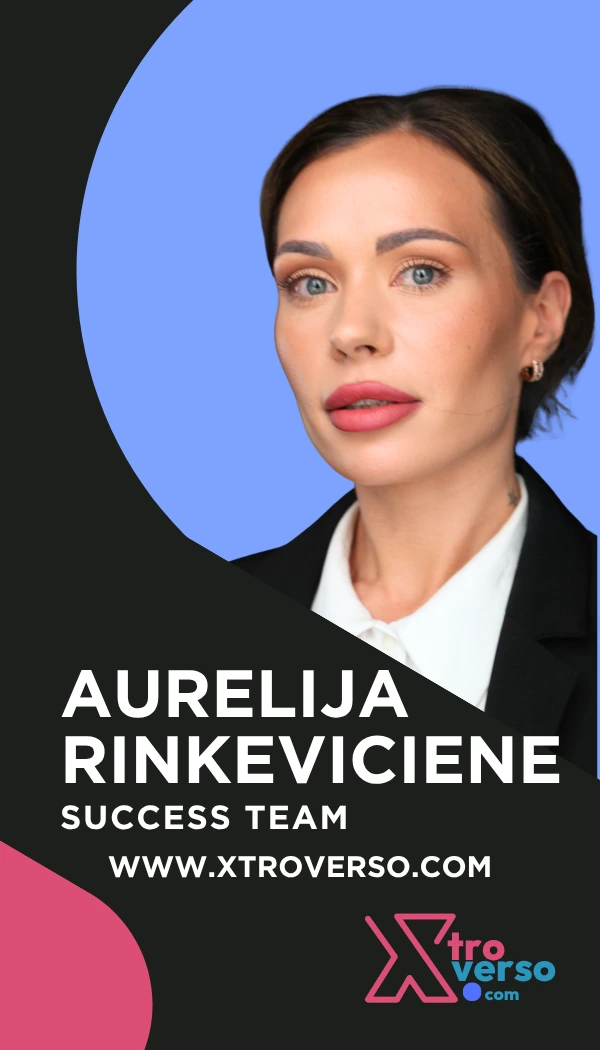
    Aurelija

    Aurelija, con su empatía natural y su fuerte sentido de cuidado hacia el cliente, se asegura de que cada cliente se sienta escuchado, apoyado y valorado. Ella está dedicada a la construcción de relaciones a largo plazo y aporta claridad, calidez y coherencia en cada contacto, fortaleciendo así la confianza y mejorando aún más la experiencia del cliente.

    RESERVA UNA REUNIÓN

    Etiquetas
    Belastingdienst DGA payroll DGA salary Dutch BV Dutch BV salary LEDGER & TAX customary wage gebruikelijk loon low DGA salary 2026 payroll tax substantial interest
    Nuestros blogs
    • LINDA PAVAN
    • IVA
    • FACTURACIÓN Y LIBRO MAYOR
    • NÓMINA
    • Governance
    • Real Estate

    Leer siguiente
    Por qué los contratistas y empleados nunca deben ser tratados descuidadamente en los libros
    En la administración empresarial holandesa, la diferencia entre un zzp’er y un empleado no es cosmética. Afecta la nómina, impuestos, flujo de caja, exposición legal y la fiabilidad de tus registros financieros.
    XTROVERSO

    Inteligencia artificial + experiencia humana + supervisión profesional.

    Servicio

    Cómo funciona Tu mejor descanso Alcance del trabajo Por qué diferente FAQ

    Marco

    Marco y controles Verificación Manifiesto cultural

    Práctica

    Sobre XTROVERSO Trabaja con nosotros Sala de prensa Contacto Reserva intake Portal del cliente Pavan Geraedts ↗

    Legal

    Términos y condiciones Declaración de privacidad Política de cookies

    Práctica responsable

    XTROVERSO

    Administración empresarial para ZZP y VOF

    Declaración de IVA y depósito con Pavan Geraedts Adviseurs

    Oficina

    De Stuwdam 33-35

    3815 KM Amersfoort

    Países Bajos

    Reuniones solo con cita previa

    Contacto

    +31 (0)85 401 9174

    hello@xtroverso.com

    KvK 70402787

    VAT NL858307790B01

    BECON 685811

    Límite profesional

    Administración a cargo de XTROVERSO

    Declaración de IVA y depósito a cargo de Pavan Geraedts Adviseurs (siempre incluidos); revisión fiscal adicional cuando el paquete lo requiere

    XTROVERSO y Pavan Geraedts Adviseurs actúan como despachos coordinados. Las responsabilidades quedan definidas en el paquete aplicable y en las condiciones del encargo.

    © 2017–2026 XTROVERSO. Todos los derechos reservados.

    XTROVERSO™

    Administración empresarial para autónomos (ZZP) y VOF en los Países Bajos, con revisión fiscal coordinada cuando el paquete lo requiere.

    XTROVERSO es un nombre comercial registrado de WIGEPA B.V. La declaración de IVA y el depósito los realiza siempre Pavan Geraedts Adviseurs bajo su propia responsabilidad profesional; los demás servicios fiscales siguen el paquete.

    • 2017-26  © XTROVERSO 
      KvK: 70402787
      BTW: NL858307790B01
      BECON: 685811

    Explorar
    • Nosotros 
    • Conocimiento
    • Contacto
    • Preguntas frecuentes
    • TRABAJA CON NOSOTROS
    • SALA DE PRENSA
      Reserva tu intake
    • Acceso cliente
    Servicios
    • Alcance del trabajo
    • Cómo funciona XTROVERSO
    • Reserva tu intake
    Marco

    Cómo funciona XTROVERSO
    Por qué XTROVERSO es diferente
    Framework & controles
    Verificación & compliance
    Manifiesto cultural

    Legal

    Términos y condiciones
    Datos & privacidad
    Política de cookies

    Oficina
    De Stuwdam 33
    3815 KM Amersfoort
    Países Bajos

    Abrir mapa

    Website Logo

    Respetar tu privacidad es nuestra prioridad.

    ¿Permitir el uso de cookies de este sitio web en este navegador?

    Utilizamos cookies para ofrecer una experiencia mejorada en este sitio web. Puedes aprender más sobre nuestras cookies y cómo las usamos en nuestro Cookie Policy.

    Permitir todas las cookiesSolo permitir cookies esenciales